
Every week we hear the same frustration from local property owners and fleet managers. You notice a crack expanding across a company car or family vehicle, and you immediately start calculating the hit to your budget.
Our team wants to clarify a major point of confusion regarding the free windshield replacement florida drivers frequently ask about. From what we see every day, understanding a specific state insurance regulation makes the difference between paying nothing and getting an unexpected bill.
This guide breaks down the exact requirements you must meet to avoid a charge. We will also show you how to verify your policy instantly and explain why you have the final say on the repair shop.
The good news is that the $0 price tag is entirely real.
The short answer
If you carry comprehensive coverage on a vehicle registered in Florida, your windshield replacement may have no out-of-pocket cost under the deductible waiver, subject to your policy and insurer confirmation. We confirm your expected cost before work begins.
This protection comes directly from the florida statute 627.7288 windshield mandate. The state actively enforces this rule to ensure drivers do not delay fixing critical safety hazards just to save money.
Without this insurance coverage, you will face significant out-of-pocket expenses to restore your vehicle:
- Standard Glass Replacement: Typically averages between $250 and $600.
- Advanced Glass (ADAS): Frequently exceeds $1,200 due to complex sensors.
We handle these claims directly with carriers every single day to save drivers from that expense. When you schedule a mobile windshield replacement with our crew, qualifying claims are billed directly to your insurance company. We confirm your expected cost before work begins.
Who actually qualifies
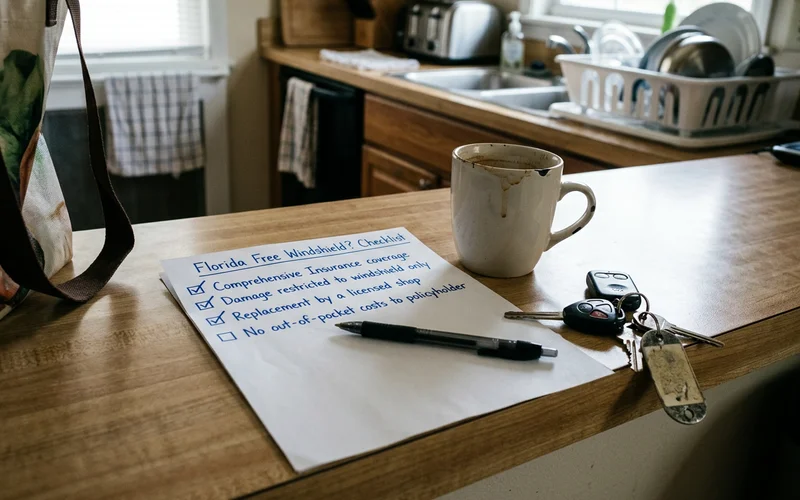
Three specific conditions must line up perfectly for your claim to be fully covered. Miss any one of these requirements, and the financial responsibility shifts back to you.
You Must Carry Comprehensive Coverage
The state of Florida only legally requires drivers to hold Personal Injury Protection (PIP) and Property Damage Liability (PDL) policies. These basic minimums cover injuries and other people’s property, but they do not cover your own vehicle damage.
To secure a zero deductible windshield florida residents must carry comprehensive coverage. This tier protects you against non-collision risks like theft, hurricanes, or a rock flying off a dump truck. Liability-only policies will leave you paying out of pocket.
Your Policy Must Be Issued in Florida
The statute explicitly applies to policies written and delivered within the state of Florida. Snowbirds and visitors often face confusion on this specific detail.
If you are a part-time resident driving a car insured in Michigan or New York, your home state rules travel with you. Most other states do not waive glass deductibles, meaning you will owe money for the repair.
The Damage Must Be on the Windshield
Florida law restricts this waiver specifically to the front windshield. Your comprehensive policy still covers other auto glass, but the standard rules apply.
Here is how different glass locations are treated by insurance:
- Front Windshield: $0 deductible under Florida law.
- Side Windows: Normal comprehensive deductible applies.
- Rear Glass: Normal comprehensive deductible applies.
- Sunroofs: Normal comprehensive deductible applies.
What “free” does and doesn’t include
The term free covers the complete structural replacement of the front glass, but it has specific boundaries. Understanding what the insurer pays for helps you set the right expectations for your appointment.
Our technicians perform replacements on highly advanced modern vehicles, which require much more than just swapping out a piece of glass. Features like lane departure warnings and automatic emergency braking rely on cameras mounted directly behind the rearview mirror.
When a new windshield goes in, these Advanced Driver Assistance Systems (ADAS) must be precisely recalibrated to function safely. A standard ADAS calibration costs anywhere from $150 to $650 out of pocket. The good news is that if the vehicle manufacturer requires this calibration, your comprehensive claim may cover the cost, subject to policy terms and insurer confirmation.
| Covered by the $0 Waiver | Not Covered (Deductible Applies or Cash) |
|---|---|
| The standard or advanced windshield itself | Side glass, back glass, and sunroofs |
| New mouldings, clips, and professional adhesive | Cosmetic tint upgrades not originally on the vehicle |
| Transfer of rain sensors and camera brackets | OEM glass (unless specifically endorsed by your policy) |
| Mandatory ADAS safety recalibration | Damage on a vehicle lacking comprehensive coverage |
How to check your coverage in two minutes
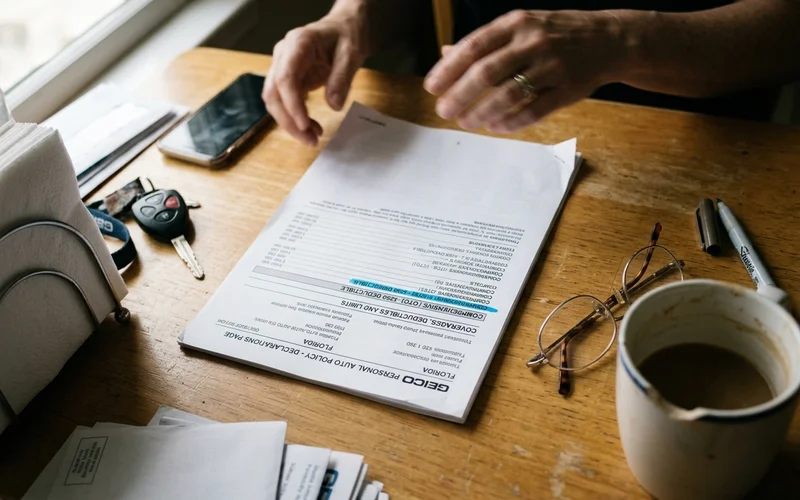
You do not need to call an agent and wait on hold to figure out your standing. Open your insurance app or pull out the declarations page that came with your policy and look for a line that says Comprehensive or Other Than Collision.
There will be a dollar figure next to that line, which is usually $500 or $1,000. That figure is your deductible for things like hail damage or theft, but for a front windshield claim in Florida, that number gets waived to zero.
Our office verifies coverage with carriers all the time, and we can tell you quickly if you have the right policy. Drivers with auto loans are almost always covered. If you finance or lease your vehicle, your lender almost certainly required you to carry comprehensive insurance to protect their collateral.
If you cannot locate your paperwork, the fastest route is to send us a photo of your insurance card along with your year, make, and model.
Ask before you assume
Policies get changed at renewal without much fanfare. Plenty of drivers discover their agent moved them to liability-only to lower the premium. Two minutes of checking beats a surprise on install day.
Can your insurer make you use their shop?
No. Florida drivers have the absolute right to choose who performs the work on their vehicle.
Your carrier may suggest a specific business from their preferred network. There is nothing inherently wrong with those shops, but a recommendation is never a legal requirement. Florida Statute 626.9743 strictly prohibits insurance companies from forcing you to use a mandatory repair location.
We often hear from customers who felt pressured by subtle tactics on the phone. Sometimes, the phone representative handling your claim actually works for a Third-Party Administrator (TPA) that owns its own auto glass shops. They might imply that choosing an independent shop is risky, which is highly misleading.
Common Warning Signs on the Phone
Insurance representatives use specific phrases to keep you in their corporate network. Be prepared for these common statements:
- “You will have to pay the difference out of pocket.” (False, the state requires full coverage of a fair market rate).
- “We cannot warranty the glass if you use them.” (True, but the independent shop provides their own superior warranty).
- “Your claim will take much longer to process.” (False, processing times are regulated heavily by the state).
We work with all major insurance companies, accept insurer-approved rates, and assist with claims and direct billing. We confirm your expected cost before work begins.
Does the waiver cover chip repair too?
The $0 deductible language in Florida Statute 627.7288 is written specifically for windshield replacement. In practice, most insurers also cover a small chip repair at low or no cost, because a repair is far cheaper for them than a replacement later. That is a carrier practice, not the statute, so coverage can vary by company.
ClearShield specializes in replacement and does not perform chip repair ourselves. If your damage is a small, contained chip that a glass-only repair shop can fill, we are happy to point you toward one in your area. If the damage has spread, sits in the driver’s sightline, or reaches the edge of the glass, replacement is the only safe option and that is exactly what we do.
The catch is the short window of opportunity. Florida weather creates a rapid phenomenon called thermal shock. When your car bakes in the afternoon sun, the glass expands, and the moment you blast the cold air conditioning, the rapid contraction forces even a small chip to split across the windshield. What looked like a ten-minute repair in the morning is a full replacement by dinnertime.
Repair vs. Replacement Checklist
- May qualify for repair: Smaller than a quarter, positioned away from the edge, not in the driver’s direct view. A glass-only repair shop handles this.
- Requires replacement: Larger than a quarter, cracks touching the glass edge, damage in front of the steering wheel, or any crack that has started to run.
The question everyone asks next
Almost every customer wants to know if using this state benefit will increase their premiums down the line. Drivers worry that claiming a free windshield now means paying for it later in higher monthly rates.
A glass claim in Florida is filed as a non-fault comprehensive incident. Carriers treat these completely differently than an at-fault collision. Replacing the glass is actually a matter of legal compliance, as Florida Statute 316.2952 allows law enforcement to issue a citation if a damaged windshield obstructs your clear view of the road.
We have unpacked exactly how the rating systems work in our detailed guide on whether a windshield claim raises your insurance rates. Reading through that resource will give you a clear picture of how carriers view these specific safety claims.
What to do with a cracked windshield right now
Florida weather gives you very little time to wait on damaged glass. A minor chip that would stay put in a cooler state will quickly split across your entire windshield in our intense humidity and heat.
You need to take action before a small chip turns into a mandatory, time-consuming replacement. If you are still wondering is windshield replacement free florida regulations are firmly on your side.
Our crew makes the next step incredibly simple. Send us a clear photo of the damage along with your vehicle details, and we will quickly confirm your comprehensive coverage status.
If your policy covers the damage, you can immediately book a mobile van to meet you right where your car is parked.